Jasmine Hallam
“After contacting many other brokers and having no luck to obtain our forever home we found Vince and his team”
Buying or refinancing residential or commercial property? Growmore Capital helps self-employed Australians explore lending options using an accountant’s letter, without always needing tax returns or full financial statements.
Alternative income documentation. Experienced lending advice. Clear answers.
Check My Lending OptionsLoan eligibility and documentation requirements vary by lender.
Answer a few quick questions so we can understand your situation and review the lending options that may suit you.
“After contacting many other brokers and having no luck to obtain our forever home we found Vince and his team”
“Thanks Vince for assisting us to obtain our loan. You’re professional, dedicated and have remarkable competence.”
“We went through a few brokers but he was the only guy to get it done.”
You've worked hard to build your business.
But when you apply for a mortgage, suddenly things get complicated.
Your tax returns might not reflect what you're currently earning. Your income comes through a company or trust. The bank keeps asking for more documents.
Maybe you've already spoken with another broker.
They sounded confident at the start. Then the updates stopped, the application dragged on, or the lender said no.
You don't want to keep starting again. You want someone who understands your situation and can give you a straight answer.
We work with self-employed borrowers whose income doesn't always fit traditional bank lending requirements.
Instead of looking only at your tax returns, we take the time to understand your business, current income, property and borrowing requirements.
Then we assess suitable lending options, including lenders who may accept accountant letters and alternative income documentation.
With 20 years' industry experience and a background in credit assessment for banks and private lenders, we understand how lenders assess complicated applications.
We Look at the Whole Picture, Explain What's Possible, and Manage the Application Through to Settlement.
No guessing. No unnecessary runaround. And no chasing us for updates.
Here's what Growmore Capital provides.
We look at your business income, debts, property and borrowing requirements so you understand what may be possible.
We assess whether suitable lenders may accept accountant-confirmed income instead of relying solely on traditional income documents.
We compare suitable lender requirements, rates, fees and loan structures before recommending a path forward.
We consider your credit position to help identify problems that could affect an application.
You'll understand the proposed loan's requirements and financial implications before deciding whether to proceed.
We follow up with lenders, valuers and solicitors and help manage outstanding requirements.
We keep you informed and respond to calls and messages within one business day.
One Experienced Team. A Clear Lending Plan. Someone Taking Responsibility for Your Mortgage Application.
Complete the short mortgage assessment quiz. Tell us whether you're buying, refinancing or accessing equity, and a little about your income situation.
We review your situation, identify suitable documentation and lender requirements, and explain the options that may be available.
If you choose to proceed, we manage the lending application, follow up with the relevant parties and support you through to settlement.
All loans remain subject to the lender's eligibility criteria, assessment and approval.
We've worked in credit assessment at banks and private lenders, which means your application is reviewed by people who understand how lending decisions are assessed.
We assess alternative income documentation, which means you may have options beyond traditional tax returns and financial statements.
We understand business structures, which means your lending options can be considered in the context of how your income is earned.
We review potential credit issues, which means possible problems may be identified before another application.
We compare suitable policies, which means you're not relying on one bank's rules to determine your options.
We keep you informed, which means you're not left chasing your broker to find out what's happening.
We follow up with lenders, valuers and solicitors, which means someone is managing outstanding finance requirements.
You understand what borrowing options may be available, what documents are needed and what the costs could look like.
You're not chasing your broker or wondering whether another bank application will go nowhere.
You've got someone experienced explaining the decisions, following up on the details and keeping you informed.
And when a suitable loan is approved, you can move forward with your property purchase or refinance knowing the finance has been properly assessed.
Less Confusion. More Clarity. A Mortgage Process You Can Actually Understand.
| THE COMMON FRUSTRATION | THE GROWMORE APPROACH |
|---|---|
Applications submitted without enough understanding of the income. | We assess the financial position and lender policies before recommending the next step. |
Brokers who don't understand company or trust income. | We work with self-employed borrowers and complex borrowing structures. |
Being left chasing application updates. | We commit to responding within one business day and updating you at important stages. |
Confusing loan fees and conditions. | We explain lender requirements, potential costs and loan structures in plain English. |
Lenders repeatedly requesting documents. | We coordinate documentation requirements and follow-ups to help avoid unnecessary delays. |
Problems identified too late. | We review borrowing requirements and potential credit issues early in the process. |
The Difference Isn't Another Promise of Easy Approval. It's How We Assess, Explain and Manage Your Finance.
You Shouldn't Have to Chase Your Mortgage Broker to Find Out What's Happening.
That's why we commit to:
Tell us. We'll acknowledge the issue, explain what happened and agree on how we'll put it right.
We explain potential lender fees, charges and loan conditions so you can assess the costs before deciding whether to proceed.
Different property goals. Different business incomes. See the kinds of situations Growmore Capital can help explore.
Looking for: A mortgage to buy a family home
How Growmore could help: Explore low-doc options and what income documents a lender may accept.
What they got out of it: A clear picture of which low-doc home loan options fit his situation, and exactly what to prepare before applying.
Looking for: A mortgage to buy an investment property
How Growmore could help: Review suitable lending options and alternative ways to verify business income.
What they got out of it: A shortlist of lenders open to alternative income verification for her investment purchase.
Looking for: A mortgage refinance
How Growmore could help: Review the existing mortgage and explain whether a low-doc refinance option may suit.
What they got out of it: A straight answer on whether refinancing made sense for him, and the exact steps to move forward.
Looking for: Finance for a commercial property
How Growmore could help: Explore possible finance options and explain the documents needed for the application.
What they got out of it: A clear list of finance pathways and the exact documents needed to move her application forward.
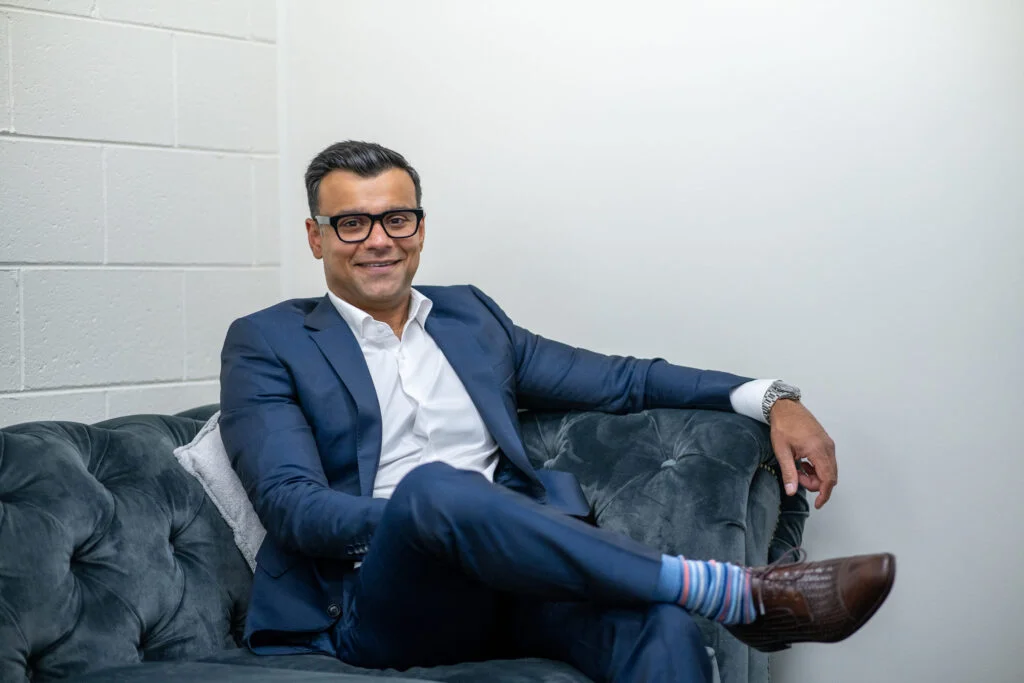
With 20 years in the lending industry, Vince has worked in credit assessment at banks and private lending offices.
He's also been involved in property development himself.
That combination gives him a practical understanding of how lenders think, how property transactions work and why the right loan structure matters.
At Growmore, the focus is on understanding your circumstances, explaining the available options and taking responsibility for the application process.
Experienced Advice. Straight Answers. Client First.
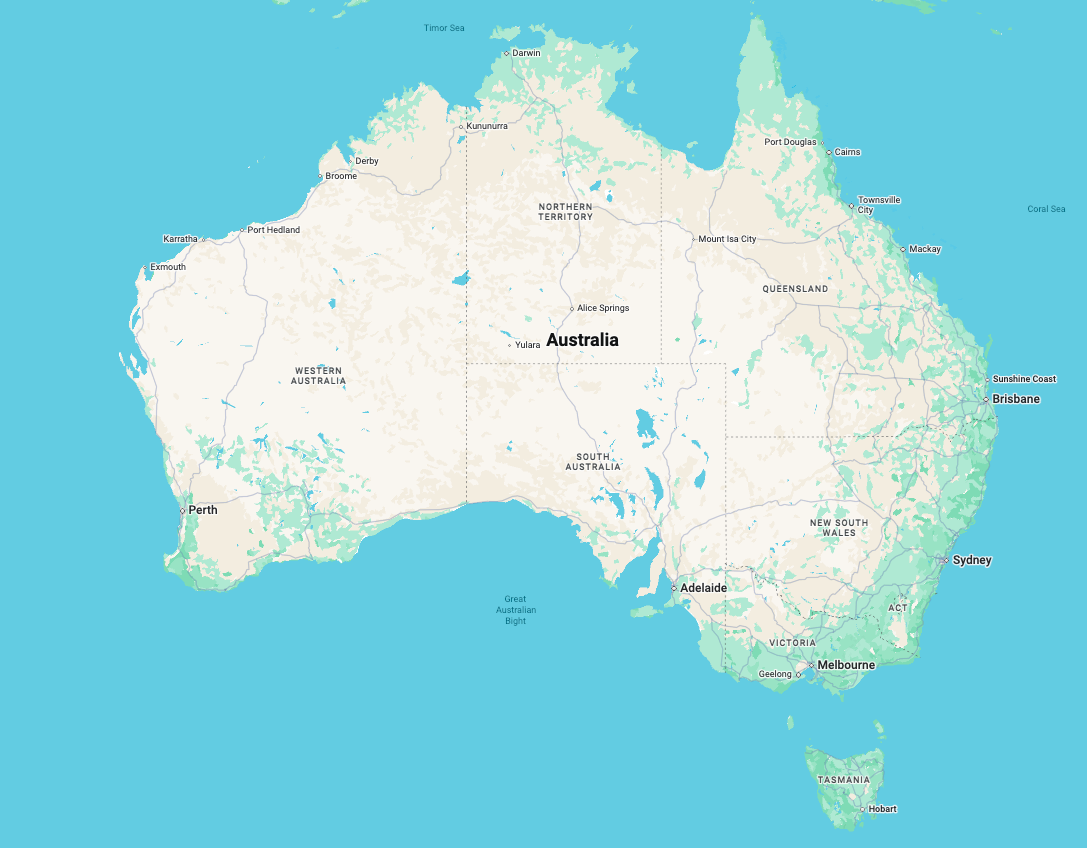
Growmore Capital works with borrowers looking to buy or refinance property across Melbourne, Sydney, Brisbane, the Gold Coast, Adelaide and Perth.
Whether you're purchasing residential or commercial property or refinancing an existing loan, we can assess your circumstances and discuss suitable lending options.
Whether you're buying a property, refinancing or accessing equity, start with an experienced assessment of your mortgage options.
If you have a purchase or settlement deadline approaching, getting the assessment started early can help identify issues before time runs short.
20 Years' Lending Experience. Accountant-Letter Lending Options. Backed by Our No-Chasing Guarantee.
Check My Lending OptionsAll loans are subject to lender assessment, eligibility criteria and approval. Accountant-letter documentation is not accepted for every loan or borrower.